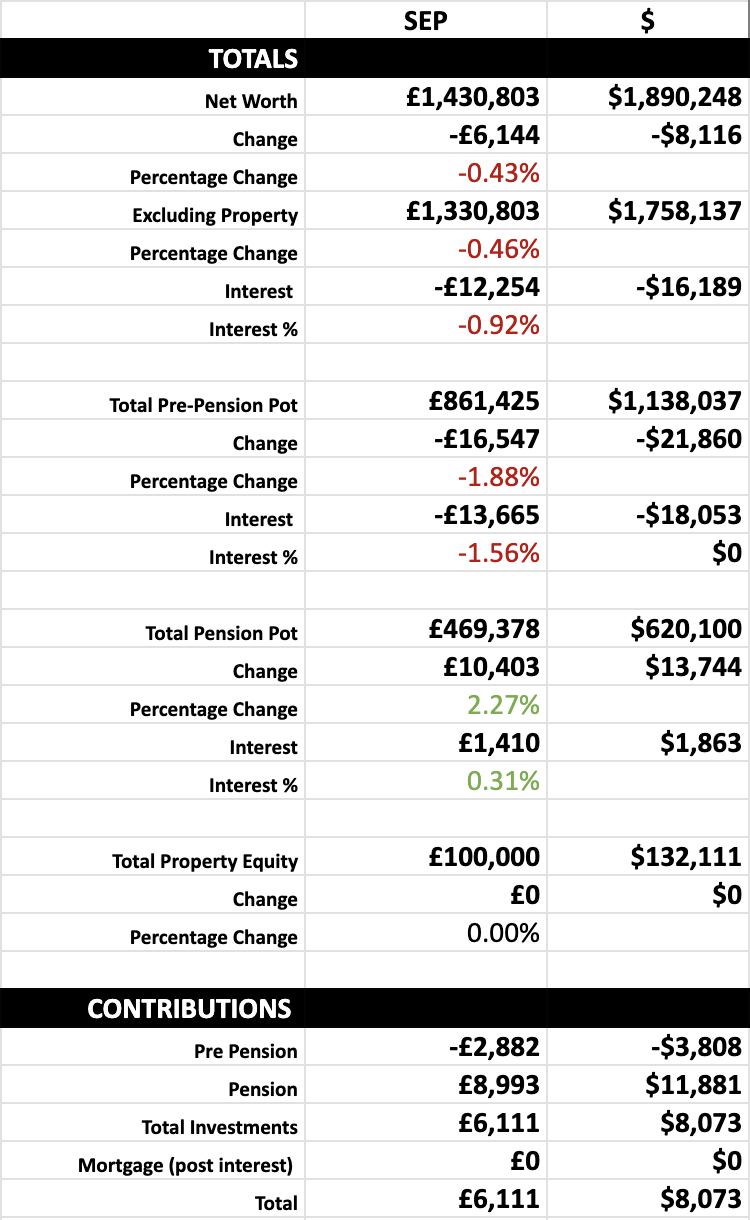
Click here to see all of my past Savings Reports and view my interactive net worth chart
Go to How To Track Your Savings to check out the Saving Ninja Super Spreadsheet.
I’ve been feeling frustrated lately.
On one hand we’re doing very well financially, but then on the other, I’m 90% confident that the writing is on the wall for software jobs. I feel it’s not a matter of if but when for there being next to no jobs left in my line of work.
This is frustrating because 5 years ago, I would have decided to retire early with the amount of money we have now. I intended to earn a side income anyway, pickup odd contracting jobs, make software, write books. That would have been our buffer, and I was also confident I’d have a job to come back to if sequence of returns risk played out on the unfortunate side.
But now, I’m not sure of any of this.
I don’t want to give up my lucrative job when it might be the last job of this salary that I can ever get.
We’re not quite financially comfortable enough for me to quit and guarantee we’ll be fine forever not earning another penny.
I can’t guarantee that I can earn a side income, in fact I’m pretty confident that I can’t any longer.
So I’m stuck in limbo looking at our pre-pension pot and wondering when it will be enough to cover a house that we want and our living expenses until retirement age. Probably working way longer than needed just to create an unbreakable buffer as I can no longer count on my capability to earn side-income.
I know I’m probably being disillusioned here. I can’t imagine the feeling of career dread for the people that don’t have these financials and are far away from retirement age.
I should count myself lucky, I know! It’s frustrating nonetheless.
I’m frustrated that this amount of money isn’t quite over the line to be true F U money in this economy and with this shortage of jobs when in any other time it would have been.
Although I am lucky that I’m still enjoying work, and for now I do have a job. If there was a big market dip, man that would suck. I’m just a bundle of anxiety aren’t I?
Whenever work gets stressful, I start thinking about either burning out or getting laid off, then I start thinking if we have enough money to survive and live the life we want and getting stressed out about that. And I haven’t even thought about drawdown strategies, we’re still in 100% equities, what if there’s a crash!? It’s a big cycle.
How to ease the dread
When I got into one of these doom cycles last year, I decided that tracking every expense would help. Then I’d know for sure if we have enough to survive and how much money we can spend on a house.
This has been helpful, but it’s also showing that we spend a lot more than I thought we did. Just this last month we spent £1k on groceries!! And none of that is from eating out, we cook everything from scratch, we even get some for free from a surplus food event each Friday.
Whenever we sit down try and figure out how we spent that much, there’s always an explanation. “Oh, we did a big Costco shop and got a lot of bulk food.” or “We ordered bulk cat biscuits and litter this month.”
We’re not spending this much every month, but it is mostly between £600 and £750 which is still not good. Has the cost of living risen that much? Or are we getting frivolous in our old, child rearing, age? 8 years ago , we used to spend £150 per month on food.
This makes me more uneasy, as it means we’re not ready to pull the plug and retire. At least not with the £500k house with land that we want, not with no prospects of side-income, this far away from being able to access our SIPP’s.
We will have to have a sit down and think at the end of this year to evaluate our investments and expenses and see if we truly are ready to retire early with no side income and what our options are. We would have collected two years of expense data by that point so should be able to make a reasonable guess.
See you next month.